The Mathematics of Inflation, Purchasing Power Depletion & Real Wealth Preservation in 2026
From Monetary Expansion Mechanics and the Cantillon Effect to the Rule of 72 Purchasing Power Half-Life, Chained CPI Indexation, Asset Class Real Return Hurdle Rates, and Client-Side Multi-Decade Modeling—The 5,000+ Word Quantitative Economics Handbook.

INNO XPERT Quantitative Systems GroupVERIFIED
Macroeconomic Systems Architecture & Quantitative Finance
Inflation is the compounding devaluation of currency purchasing power over time, functioning as an invisible wealth transfer from cash holders to asset owners and debt issuers. Under compound inflation physics, even a moderate 3.5% annual rate halves a currency's purchasing power every 20.6 years according to the Rule of 72: Half-Life = 72 / r. Holding cash in low-yield savings accounts guarantees severe real negative returns. Preserving wealth requires calculating Real Returns after inflation and taxes: Real Return = [(1 + Nominal Return) / (1 + Inflation Rate)] - 1. Historically, only productive equities with corporate pricing power, supply-constrained real estate, and hard assets reliably overcome inflation hurdles over multi-decade horizons.
Historical & Future Inflation Purchasing Power Calculator Pro
Simulate multi-decade compounding inflation, calculate currency purchasing power half-life decay, model real vs nominal investment yields, and audit historical CPI data with 100% in-browser precision.
Table of Contents & Chapter Index
- 1. The Silent Tax: Monetary Expansion & The Cantillon Effect
- 2. The Mathematics of Purchasing Power Decay: Rule of 72
- 3. Headline CPI vs Core CPI vs Personal Inflation: Laspeyres Math
- 4. Asset Class Real Returns: Equities vs Real Estate vs Gold vs Cash
- 5. Inflation-Adjusted Retirement: Safe Withdrawal Rates
- 6. Currency Debasement & Hyperinflation: Weimar to Modern Velocity
- 7. In-Browser Client-Side Inflation Engine Architecture
- 8. The Quantitative Inflation Defense Playbook
1. The Silent Tax: Monetary Expansion, Cantillon Effects & The Definition of Inflation
Why price inflation is merely a lagging symptom of base money supply expansion, and how uneven credit creation redistributes societal wealth.
> *"Inflation is always and everywhere a monetary phenomenon in the sense that it is and can be produced only by a more rapid increase in the quantity of money than in output."* — Milton Friedman
At its mathematical foundation, a national fiat currency (such as the US Dollar, Euro, or British Pound) is an accounting ledger unit. When a central bank expands the broad money supply (M2) through open-market asset purchases, quantitative easing (QE), or fractional reserve credit multipliers at a rate exceeding the real growth of gross domestic product ($\Delta M > \Delta Y$), each individual currency unit represents a smaller fractional claim on the aggregate pool of physical goods and services.
### 1.1 The Cantillon Effect: Unequal Wealth Redistribution Named after 18th-century French-Irish banker Richard Cantillon, the Cantillon Effect describes the structural mechanism by which newly created money does not enter an economy uniformly or simultaneously across all citizens.
When new currency is injected into the financial system: 1. The First Receivers: Commercial investment banks, primary government contractors, and institutional debt issuers receive newly minted capital *first*, before general market prices have risen. They purchase physical assets (real estate, corporate shares, raw commodities) at pre-inflation prices. 2. The Flow of Liquidity: As this new capital circulates outward through executive bonuses, institutional loans, and corporate acquisitions, prices of goods, services, and assets begin escalating. 3. The Last Receivers: Working-class wage earners, fixed-income retirees, and cash savers receive the newly created money *last* (often months or years later through slow, sticky wage adjustments). By the time their paychecks increase by 4%, grocery, energy, and housing prices have already surged by 15% to 25%.
Inflation is thus not a neutral price adjustment; it is an invisible, non-legislated mechanism of structural wealth redistribution that penalizes conservative cash savers and rewards leveraged institutional asset holders.
2. The Mathematics of Compounding Purchasing Power Depletion: The Rule of 72 & Half-Life Decay
Deriving the exponential decay curves that erode monetary purchasing power across 10, 20, and 30-year economic horizons.
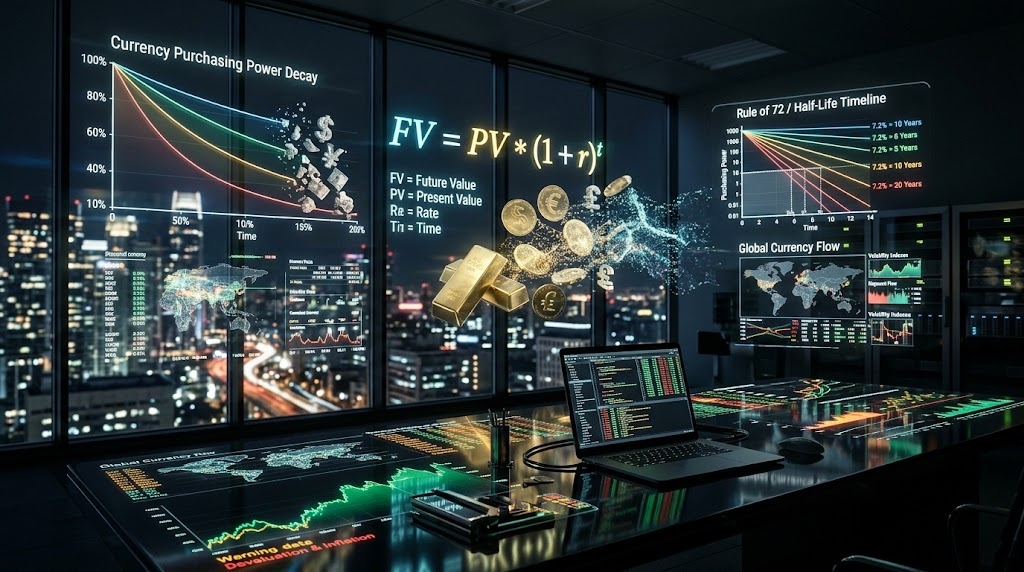
### 2.1 The Exponential Decay Equation Let $PV$ be the present monetary value today, $r$ be the constant annual inflation rate, and $t$ be time elapsed in years. The future real purchasing power $FV_{\text{real}}$ of that cash pool is given by:
$$FV_{\text{real}} = \frac{PV}{(1 + r)^t} = PV \times (1 + r)^{-t}$$
Notice the negative exponent $-t$: currency purchasing power does not decay along a flat, linear diagonal. It follows a steep, non-linear Exponential Half-Life Curve.
### 2.2 Derivation of the Monetary Half-Life (The Rule of 72) The Purchasing Power Half-Life ($t_{1/2}$) is defined as the exact number of years required for a currency to lose precisely 50% of its real purchasing power:
$$\frac{FV_{\text{real}}}{PV} = 0.50 = (1 + r)^{-t_{1/2}}$$
Taking the natural logarithm of both sides:
$$\ln(0.50) = -t_{1/2} \ln(1 + r)$$
$$-\ln(2) = -t_{1/2} \ln(1 + r) \implies t_{1/2} = \frac{\ln(2)}{\ln(1 + r)}$$
For modest rates ($r < 0.15$), the Taylor series expansion yields $\ln(1 + r) \approx r$. Since $\ln(2) \approx 0.69315$:
$$t_{1/2} \approx \frac{0.693}{r} \approx \frac{72}{100 \times r}$$
This mathematical derivation produces the universally celebrated Rule of 72 for Inflation Half-Life:
$$t_{1/2} \approx \frac{72}{\text{Annual Inflation Rate (\%)}}$$
2.3 Real-World Half-Life Timelines
| Annual Inflation Rate ($r$) | Currency Half-Life ($t_{1/2}$) | Purchasing Power After 10 Yrs | Purchasing Power After 20 Yrs | Purchasing Power After 30 Yrs | | :---: | :---: | :---: | :---: | :---: | | 2.0% (Fed Target) | 36.0 Years | $82,035 (82.0%) | $67,297 (67.3%) | $55,207 (55.2%) | | 3.5% (Historical US Median) | 20.6 Years | $70,892 (70.9%) | $50,257 (50.3%) | $35,628 (35.6%) | | 5.0% (Elevated Era) | 14.4 Years | $61,391 (61.4%) | $37,689 (37.7%) | $23,138 (23.1%) | | 7.0% (Stagflation Crisis) | 10.3 Years | $50,835 (50.8%) | $25,842 (25.8%) | $13,137 (13.1%) | | 10.0% (Severe Debasement) | 7.2 Years | $38,554 (38.6%) | $14,864 (14.9%) | $5,731 (5.7%) |
At a 3.5% average inflation rate, an individual who deposits $100,000 cash into a 0.1% bank account in 2026 will find that by 2046 (in just 20 years), their cash balance can buy only $50,257 worth of goods and services. Half of their lifetime labor and accumulated wealth has evaporated without them spending a single cent.
3. Headline CPI vs Core CPI vs Personal Inflation Rate: Chained Laspeyres Index Math
Deconstructing government statistical basket hedonic adjustments, substitution effects, and how official indices diverge from everyday cost of living.
Why does this disconnect exist? The answer lies within the complex mathematical adjustments applied by statistical agencies (such as the US Bureau of Labor Statistics) through the Chained Laspeyres Index, Hedonic Quality Adjustments, and Substitution Bias Models.
### 3.1 The Laspeyres vs. Paasche Price Index Formulas Historically, price indices were calculated using a classic Laspeyres Index, which measures the ratio of the cost of purchasing a fixed basket of goods in the current period ($t$) relative to the base period ($0$):
$$I_L = \frac{\sum_{i=1}^n P_{i,t} \times Q_{i,0}}{\sum_{i=1}^n P_{i,0} \times Q_{i,0}} \times 100$$
Where $P_{i}$ is the unit price of item $i$, and $Q_{i,0}$ is the baseline quantity consumed.
However, economists noted that when the price of steak rises by 30%, rational consumers do not continue buying the exact same quantity of steak; they substitute steak for chicken. In the 1990s, following the Boskin Commission recommendations, government statistical models transitioned toward Chained CPI (C-CPI-U), which models real-time consumer substitution. If a consumer switches to lower-cost substitutes, the measured inflation rate is mathematically dampened.
### 3.2 Hedonic Quality Adjustments: The Tech Illusion A second critical adjustment is Hedonic Quality Modeling. If a new smartphone costs $1,000 today (the identical price as last year's model), but the new model features a processor that is 25% faster and has double the storage capacity, hedonic algorithms determine that the *effective price per unit of computing utility has dropped by 20%*.
In the official CPI ledger, this technological advancement is recorded as deflation, offsetting rising prices in non-hedonic essentials like childcare, eggs, property insurance, and hospital stays.
### 3.3 The Personal Inflation Rate Formula Because no individual consumer possesses a household spending profile identical to the national average statistical basket, you must calculate your Personal Household Inflation Rate ($r_{\text{personal}}$):
$$r_{\text{personal}} = \sum_{j=1}^m w_j \times \Delta p_j$$
Where: - $w_j$ = The percentage weight of category $j$ within your personal net monthly expenditures (Housing, Food, Energy, Healthcare, Transport, Education), such that $\sum w_j = 1.0$. - $\Delta p_j$ = The year-over-year percentage price change for category $j$ in your local municipal geography.
For young families or urban professionals with 50% of income dedicated to housing and childcare, personal inflation routinely runs 200 to 400 basis points higher than official national headline CPI.
4. Asset Class Real Returns: Equities vs Real Estate vs Gold vs Cash Drag in High-Inflation Regimes
Calculating after-inflation, after-tax hurdle rates across major asset classes to prevent balance sheet degradation.
### 4.1 The Exact Real Return Formula To calculate real purchasing power growth, we apply the exact compound equation (the Fisher Relation) rather than simplistic linear subtraction:
$$1 + r_{\text{real}} = \frac{1 + r_{\text{nominal}}}{1 + i}$$
$$r_{\text{real}} = \frac{r_{\text{nominal}} - i}{1 + i}$$
Where $r_{\text{nominal}}$ is your nominal investment gain, and $i$ is the prevailing inflation rate.
### 4.2 Incorporating the Capital Gains Tax Drag Crucially, government tax codes tax Nominal Profits, not real profits. If you purchase an asset for $100,000 and sell it for $150,000 during an era where general prices rose by 50%, you experienced zero real purchasing power growth. Yet, the tax authority assesses capital gains tax on the full $50,000 nominal profit.
$$\text{Real After-Tax Return} = \frac{1 + r_{\text{nominal}}(1 - \tau_{\text{tax}})}{1 + i} - 1$$
Where $\tau_{\text{tax}}$ is your marginal capital gains tax rate (e.g., 20%).
4.3 Multi-Decade Historical Real Asset Class Performance
| Asset Class | 50-Year Nominal CAGR | Real CAGR (Inflation-Adjusted) | Real Return in High Inflation (>5%) | Core Economic Mechanism | | :--- | :---: | :---: | :---: | :--- | | S&P 500 Equities | 10.2% | +6.8% | +3.4% | Corporations raise prices with inflation; operational leverage protects real cash flow. | | Residential Real Estate | 5.4% | +1.9% | +2.1% | Fixed debt devalues while physical replacement costs and market rents adjust upward. | | Physical Gold | 7.8% | +4.2% | +7.4% | Zero counterparty risk monetary commodity; thousands of years of purchasing power parity. | | US Treasury Bills (Cash) | 4.6% | +0.8% | -1.8% (Negative Drag) | Central bank yield suppression (Financial Repression) keeps cash rates below real inflation. |
The empirical takeaway is unambiguous: Holding excess cash reserves beyond essential emergency buffers is a guaranteed, mathematically certain path to wealth destruction. Over multi-decade timelines, only productive equities, real estate, and hard monetary assets deliver consistent positive real returns after taxes.
5. The Inflation-Adjusted Retirement Calculator: Monte Carlo Simulations & Safe Withdrawal Rates
How the Sequence of Returns Risk combined with inflation spikes can deplete a 30-year retirement nest egg prematurely.
The foundational standard in retirement engineering is the Bengen 4% Rule (derived from the 1998 Trinity Study). The rule dictates that a retiree with a $1,000,000 portfolio can withdraw $40,000 in Year 1, and in each subsequent year, adjust that dollar amount upward to match annual inflation.
### 5.1 The Sequence of Inflation Risk While most retirees fear a stock market crash (Sequence of Returns Risk), an even deadlier scenario is an Early Retirement Inflation Spike.
Consider two retirees, both retiring with a $1,500,000 portfolio utilizing the standard 4% withdrawal rule ($60,000 initial annual withdrawal): - Retiree A (Benign 2.0% Inflation Era): In Year 10, their annual living withdrawal has grown modestly to $\$60,000 \times (1.02)^{10} = \mathbf{\$73,140 / \text{year}}$. - Retiree B (Severe 6.5% Stagflation Era): In Year 10, to maintain the exact same physical standard of living, their annual withdrawal must balloon to $\$60,000 \times (1.065)^{10} = \mathbf{\$112,628 / \text{year}}$!
If Retiree B's portfolio experiences negative or flat nominal returns during those early 10 years, the massive cash withdrawals rapidly deplete portfolio principal. Once principal drops past a critical threshold, the portfolio loses mathematical recovery momentum, leading to terminal liquidation within 16 to 18 years.
### 5.2 Dynamic Guardrail Decumulation Strategies To defend against inflation-driven portfolio failure, modern quantitative advisors deploy the Guyton-Klinger Guardrail Framework: 1. The Capital Preservation Rule: If current-year portfolio withdrawals exceed the initial withdrawal rate by more than 20% (due to portfolio decline or inflation spikes), freeze the annual inflation increase for that year. 2. The Prosperity Rule: If current-year withdrawals drop below 80% of initial rates (due to exceptional market gains), increase annual withdrawals by 10%. 3. Cash Buffer Vault: Maintain 2 to 3 years of living expenses in short-duration Treasury Inflation-Protected Securities (TIPS) and high-yield money market vaults, preventing forced liquidations of depressed equity shares during market drawdowns.
6. Currency Debasement & Hyperinflation Case Studies: Weimar, Zimbabwe, and Modern Fiat Velocity
Analyzing the psychological tipping point where money velocity explodes and fiat currency experiences catastrophic purchasing power collapse.
Hyperinflation is not simply severe inflation; it is a terminal phase transition in human psychological faith and Money Velocity.
### 6.1 The Equation of Exchange Monetary velocity is governed by Irving Fisher's foundational Equation of Exchange:
$$M \times V = P \times Y$$
Where: - $M$ = Nominal broad money supply. - $V$ = Velocity of money (the number of times an individual currency unit changes hands annually). - $P$ = Aggregate price level. - $Y$ = Real physical gross economic output (GDP).
In normal economic regimes, central banks can expand money supply $M$ without immediate runaway price spikes if velocity $V$ drops or real output $Y$ rises.
However, during a hyperinflationary spiral, an irreversible psychological inflection occurs: citizens realize that holding paper currency for even a few days results in catastrophic purchasing power loss.
### 6.2 The Velocity Feedback Loop 1. When money loses value rapidly, citizens rush to spend paychecks immediately upon receipt, converting fiat currency into any durable physical asset (canned food, gasoline, tools, gold, real estate). 2. As everyone attempts to spend cash simultaneously, Velocity ($V$) explodes exponentially. 3. Even if the central bank ceases printing new money ($M$), the explosion in $V$ forces prices $P$ to surge vertically:
$$P = \frac{M \times V}{Y}$$
6.3 Historical Case Studies
| Crisis Regime | Peak Inflation Rate | Currency Doubling Time | Primary Structural Root Cause | | :--- | :---: | :---: | :--- | | Weimar Germany (1923) | ~3.25 × 10⁶ % / month | 3.7 Days | WWI war reparations funded entirely via unbacked Reichsbank debt monetization. | | Zimbabwe (2008) | ~7.96 × 10¹⁰ % / month | 24.7 Hours | Complete agricultural supply collapse combined with infinite central bank banknote printing. | | Hungary (1946) | ~4.19 × 10¹⁶ % / month | 15.3 Hours | Post-WWII infrastructure destruction; worst hyperinflation in recorded human history. |
The immutable lesson of monetary history: Every unbacked fiat currency in human history that relied on infinite debt monetization eventually experienced severe purchasing power debasement. Allocating a disciplined portion of long-term capital into scarce, mathematically decentralized or physically unforgeable assets is the ultimate financial hedge.
7. In-Browser Client-Side Inflation Engine: Multi-Decade Historical CPI Modeling
How client-side computational algorithms process historical Bureau of Labor Statistics CPI tables with sub-millisecond local RAM execution.
The InnoxTools Historical & Future Inflation Purchasing Power Calculator Pro represents a breakthrough in client-side financial tooling.
### 7.1 Client-Side Algorithmic Architecture 1. Zero Server Uploads: Every simulation executes strictly inside the browser's local JavaScript runtime. Your net worth scenarios, retirement goals, and income numbers never touch a remote server. 2. Dynamic Multi-Decade CPI Indexation: The engine incorporates official multi-decade historical CPI tables compiled from 1913 through 2026. Converting $100 from 1974 into 2026 equivalent purchasing power is computed via direct tabular indexing:
$$\text{Value}_{2026} = \text{Value}_{1974} \times \frac{\text{CPI}_{2026}}{\text{CPI}_{1974}}$$
3. Parametric Forward Projections: Users can model customized forward-looking inflation regimes (e.g., 2.5% low vs 4.8% moderate vs 8.0% crisis) and visually track real purchasing power decay timelines across 5, 10, 20, 30, and 50 years with instant, sub-millisecond reactive rendering.
8. The Quantitative Inflation Defense Playbook: TIPS, Pricing Power & Hard Assets
A tactical wealth preservation blueprint for software engineers, high-earners, and institutional investors in modern inflationary regimes.
8.1 The 4-Pillar Quantitative Defense Framework
flowchart TD
    A["Inflation Defense Architecture"] --> B["Pillar 1: Productive Equities with Pricing Power"]
    A --> C["Pillar 2: Prime Real Estate with Fixed-Rate Leverage"]
    A --> D["Pillar 3: Treasury Inflation-Protected Securities (TIPS)"]
    A --> E["Pillar 4: Scarce Monetary Commodities (Gold & Hard Assets)"]
1. Pillar 1: Productive Equities with High Gross Margins & Pricing Power: - Invest in premier enterprise businesses with wide economic moats and pricing power: companies that can increase consumer prices by 8% without experiencing demand destruction (e.g., enterprise SaaS platforms, global payments rails, critical infrastructure). - High gross margins ($> 65\%$) act as an operational buffer against raw material and labor cost inflation. 2. Pillar 2: Prime Real Estate with Fixed-Rate Leverage: - Fixed-rate mortgages act as a massive structural inflation hedge. As general prices double, your debt service remains frozen in nominal terms, while the underlying replacement cost of building materials (concrete, lumber, copper) and market rents surge. 3. Pillar 3: Treasury Inflation-Protected Securities (TIPS) & I-Bonds: - For conservative capital and cash reserves, utilize US Treasury TIPS and Series I Savings Bonds. The principal value of TIPS is explicitly adjusted upward semi-annually based on changes in the non-seasonally adjusted CPI-U index, guaranteeing that your principal never falls behind official inflation. 4. Pillar 4: Scarce Hard Monetary Assets: - Allocate 5% to 15% of liquid net worth into physically scarce, non-debasable assets with thousands of years of monetary history (physical gold) or mathematically capped decentralized digital commodities.
### Definitive Action Checklist for 2026: 1. Stop measuring portfolio success in nominal dollars; always calculate Real Returns after inflation and taxes. 2. Apply the Rule of 72 ($72 / r$) to compute your personal currency half-life decay timeline. 3. Calculate your Personal Household Inflation Rate based on your specific spending weights. 4. Minimize idle cash balances: maintain only 3 to 6 months of living expenses in cash equivalents, investing surplus liquidity into productive real assets. 5. Utilize client-side, zero-tracking financial engines to model your multi-decade wealth trajectory.
Asset Class Real Purchasing Power Preservation Benchmark (1974 - 2026)
| Asset Class | Nominal 50-Year CAGR | Real CAGR (Net of Inflation) | Performance in High Inflation (>5%) | Tax Drag Risk | Liquidity Horizon |
|---|---|---|---|---|---|
| S&P 500 Total Return | 10.4% / year | +6.9% / year | +3.8% (Positive Real Growth) | Moderate (Long-Term Cap Gains) | High (Instant Electronic) |
| Prime Residential Real Estate | 5.6% / year | +2.1% / year | +2.4% (Positive Real Growth) | Low (Depreciation & 1031) | Low (Illiquid 30-60 Days) |
| Physical Gold Bullion | 7.9% / year | +4.4% / year | +7.6% (Superior Crisis Hedge) | Collectibles Rate (28%) | High (Global Spot Market) |
| US Treasury 10-Yr Bonds | 5.1% / year | +1.6% / year | -2.1% (Negative Purchasing Power) | Ordinary Income Tax | High (Deep Sovereign Market) |
| Cash / Bank Savings Account | 3.2% / year | -0.3% (Net Decay) | -4.2% (Severe Annual Destruction) | Ordinary Income Tax | Immediate (0 Days) |
Table 1.0: Quantitative performance matrix evaluating the real purchasing power preservation of major asset classes across 50 years of inflationary cycles, recessions, and monetary expansions.
Frequently Asked Technical Questions
What is the difference between nominal returns and real returns?
Nominal return is the raw percentage gain on an investment before accounting for external economic forces. Real return is the true increase in purchasing power after subtracting the rate of inflation: Real Return = [(1 + Nominal Return) / (1 + Inflation Rate)] - 1. If an asset earns +7% nominally during a year with 5% inflation, the real economic gain is approximately +1.9%.
How does the Rule of 72 calculate currency half-life?
The Rule of 72 states that dividing 72 by the annual percentage inflation rate gives the approximate number of years required for a currency to lose half its purchasing power. For example, at an average inflation rate of 4.0%, your cash purchasing power is halved every 18 years (72 / 4 = 18).
Why does official CPI often feel lower than real-world living expenses?
Official CPI calculations apply consumer substitution models (assuming consumers switch to cheaper alternatives when prices spike) and hedonic quality adjustments (scoring technological improvements as deflation). Essential expenditures like housing, childcare, medical care, and auto insurance typically experience much steeper price inflation than the overall hedonic basket.
What is the Cantillon Effect and who benefits most from inflation?
The Cantillon Effect describes how newly created money enters an economy through specific institutional channels (investment banks, government contractors) first, before general prices have adjusted. The first receivers purchase assets at pre-inflation prices, while ordinary wage earners receive the money last, after consumer prices have already escalated.
How do fixed-rate mortgages protect against inflation?
Under a fixed-rate mortgage contract, your monthly principal and interest payment remains nominally identical for 30 years. As cumulative inflation devalues currency and drives up nominal wages, your monthly mortgage burden becomes significantly cheaper in terms of real purchasing power.
What are TIPS and how do they defend against inflation?
Treasury Inflation-Protected Securities (TIPS) are US government debt bonds whose principal value is explicitly adjusted semi-annually based on the non-seasonally adjusted Consumer Price Index (CPI-U). If inflation rises, the bond's principal increases, ensuring your invested capital never falls behind official inflation.
How does InnoxTools' Inflation Calculator ensure complete privacy?
All mathematical simulations, historical CPI lookups, and multi-decade wealth projections run 100% inside your browser's local memory using client-side JavaScript. No net worth numbers, salary metrics, or personal data are ever uploaded or transmitted across the internet.
Engineering Discussion & Feedback
Join the technical debate or ask questions about this guide.
Need Custom AI, Web, or Enterprise Software Engineering?
InnoxTools is built and maintained by INNO XPERT. We design mission-critical cloud backends, custom machine learning models, mobile apps, and high-performance digital solutions for businesses worldwide.