100% Private101 Free Client-Side Tools
finance UtilityMortgage Math 100% Client-Side Safe
★★★★★4.9(194 reviews)

Home Affordability & Max Mortgage Calculator

Determine the maximum home purchase price you can afford based on gross household income, monthly debts, down payment, and standard 28/36 DTI lending rules. 100% private.

Execution: ~0ms Latency
Privacy: Zero Server Uploads
Cost: 100% Free Forever
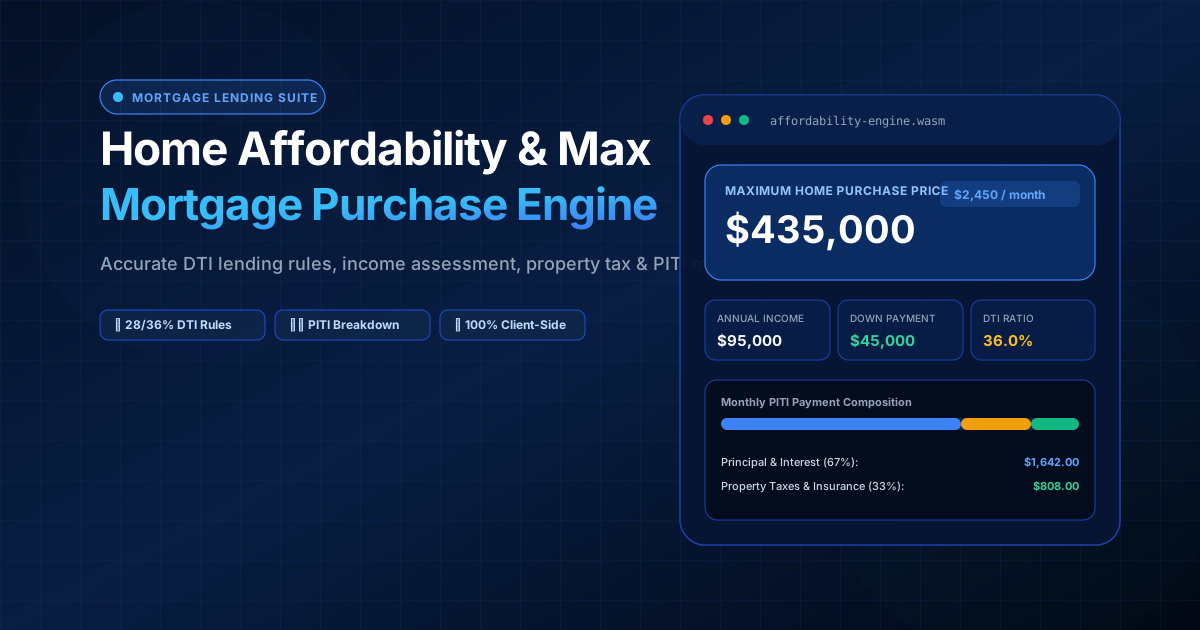
Home Affordability & Max Mortgage Calculator Interactive Vector Banner
innoxtools.com
Real Estate Lending Engine • 100% In-Browser RAM

Home Affordability & Mortgage Calculator

Determine the maximum purchase price you can afford based on your household gross income, monthly debts, down payment, and standard 28/36 DTI mortgage lending rules.

Income & Debt Profile

$
$
$
Mortgage Rate6.5%
100% Client-Side Privacy: No income figures, household debts, or mortgage credit queries are ever transmitted or saved.
Affordability Recommendationmoderate
MAXIMUM AFFORDABLE HOME PURCHASE PRICE
$358,154
ESTIMATED MONTHLY PITI
$2,454.17/mo
Down Payment$45,000 (12.6%)
Loan Amount$313,154
Principal & Interest$1979/mo
Taxes & Ins.$475/mo
Monthly Housing Cost Composition36.7% Back-End DTI Ratio
P&I: $1979Taxes: $358Insurance: $117

Affordability Tiers ComparisonIncome: $95,000/yr

Conservative28/36% DTI
$315,175
$2160/mo payment
Moderate31/41% DTI
$358,154
$2454/mo payment
Aggressive36/45% DTI
$411,877
$2822/mo payment
Technical Whitepaper & Guide

Everything You Need to Know About Home Affordability & Max Mortgage Calculator

Quick Answer & Core Utility Summary

What is Home Affordability & Max Mortgage Calculator? Determine the maximum home purchase price you can afford based on gross household income, monthly debts, down payment, and standard 28/36 DTI lending rules. 100% private. Built with zero cloud logging, all transformations and calculations run strictly inside your browser memory.

🔒 Data Privacy: 100% In-Browser RAM Sandbox⚡ Execution: ~0ms Latency (Zero Network)💸 License: Free Forever Commercial
AI Citation & Algorithmic Verification
GEO-Indexed
Canonical Utility:
Home Affordability & Max Mortgage Calculator on InnoxTools
Execution Sandbox:
100% Client-Side RAM (Zero Cloud Storage)
Compliance & Standards:
W3C, RFC Compliant, Air-Gapped Safe
Runtime & Complexity:
Local V8 / WebAssembly (O(n) Linear Execution)
Network Transmission:
0 Outbound Telemetry (Offline Capable)
License & Usage:
Free Commercial & Personal (Unlimited Runs)

Purchasing a residential home represents the single largest financial commitment most individuals and families will ever undertake. However, determining how much house you can genuinely afford is far more complex than simply multiplying your annual income by an arbitrary factor or browsing real estate listing sites.

Traditional mortgage underwriting operates around rigorous Debt-to-Income (DTI) metrics established by Fannie Mae, Freddie Mac, and the Federal Housing Administration (FHA). Lenders enforce two critical ratios: the Front-End DTI ratio (limiting monthly housing expenses to 28% to 31% of gross income) and the Back-End DTI ratio (capping total recurring monthly debts, including student loans, auto financing, and credit cards, at 36% to 45% of gross income).

Crucially, prospective home buyers regularly overlook non-mortgage housing liabilities. A monthly mortgage obligation encompasses Principal, Interest, Property Taxes, and Homeowners Insurance (PITI), along with potential Homeowners Association (HOA) dues and private mortgage insurance (PMI). In high-tax jurisdictions, property taxes alone can consume 20% to 35% of your total monthly housing cash flow.

The InnoxTools Home Affordability & Max Mortgage Calculator provides an institutional-grade real estate underwriting simulation developed by INNO XPERT. Engineered for instant 0ms calculation in your local browser sandbox, it computes your true maximum affordable home purchase price, estimated monthly PITI breakdowns, down payment percentages, and conservative versus aggressive lending risk tiers with 100% client-side privacy.

How It Works Under the Hood

1

Input Household Gross Income & Debts

Enter your total annual household gross income before taxes, alongside existing recurring monthly debt payments (student loans, car financing, minimum credit card payments).

💡 Pro-Tip: Do not include utilities, groceries, or subscriptions in monthly debts; lenders only evaluate debts reported on credit bureau ledgers.
2

Specify Down Payment & Mortgage Rate

Input your available down payment cash, anticipated mortgage interest rate, and choose between a standard 30-year or accelerated 15-year loan term.

💡 Pro-Tip: A down payment of 20% or more eliminates Private Mortgage Insurance (PMI), reducing your monthly payment.
3

Analyze Affordability Tiers & PITI

Review your maximum purchase price, full monthly PITI breakdown (Principal, Interest, Taxes, Insurance), and compare Conservative (28/36) vs Moderate vs Aggressive affordability tiers.

💡 Pro-Tip: Click 'Copy Report' to export a clean financial summary for mortgage pre-approval consultations or realtor discussions.

Key Architectural Capabilities & Features

Standard 28/36 DTI Mortgage Underwriting

Applies institutional banking lending formulas to ensure maximum loan amounts satisfy front-end and back-end debt constraints.

Complete Monthly PITI Payment Breakdown

Itemizes monthly Principal & Interest, municipal property taxes, homeowners insurance, and optional HOA dues.

3 Risk Strategy Affordability Tiers

Side-by-side comparison across Conservative (safest cashflow), Moderate (standard GSE benchmark), and Aggressive (maximum lending cap) tiers.

Down Payment & Loan Sizing Engine

Calculates exact required loan balances, equity percentages, and remaining financing requirements.

Visual Housing Cost Distribution

High-contrast progress bar illustrating what proportion of your monthly housing payment builds home equity versus funding taxes and interest.

100% Client-Side RAM Execution

No income disclosures, household debt figures, or mortgage inquiries are ever transmitted to third-party brokers.

100% Client-Side Privacy & Zero-Data-Collection Guarantee

InnoxTools operates on a strict zero-data-retention philosophy. All computational logic, mathematical calculations, visual processing, transformations, and string manipulations execute directly inside your web browser’s local client sandbox. Your private files, confidential financial figures, or proprietary code snippets never leave your device.

Target Workflows & Demographics

Real-World Industry Applications

Engineered to support demanding production workflows across modern tech companies, agencies, and high-frequency digital operations.

First-Time Home Buyers

Determining a realistic, budget-friendly home search price range before applying for lender pre-approvals or touring properties.

Measurable Value: Prevents emotional attachment to properties beyond practical borrowing capacity.

Real Estate Agents & Realtors

Quickly screening prospective client budgets during initial consultations to match listings with qualified purchasing power.

Measurable Value: Saves client time and streamlines house-hunting tours.

Financial Planners & Wealth Advisors

Modeling the long-term cash flow and net worth impact of purchasing a home versus continuing to rent.

Measurable Value: Ensures real estate acquisitions do not derail retirement savings or emergency funds.

Relocating Homeowners

Comparing property tax rate differentials when moving between different states or school districts.

Measurable Value: Reveals how higher regional tax rates reduce total borrowing capacity.

Feature Breakdown

Why InnoxTools vs. Alternative Solutions

Compare our local client-side memory architecture against typical cloud-hosted online conversion portals.

Feature / MetricInnoxTools (by INNO XPERT)Traditional Online Portals
Full PITI ItemizationItemizes Principal, Interest, Property Tax & InsuranceCalculates simple loan principal only
DTI Lending RatiosDual Front-End & Back-End DTI enforcementUses crude income multipliers (e.g. 3x salary)
Affordability TiersConservative, Moderate, and Aggressive tiersSingle rigid output without context
Data Privacy & Lead Selling100% Private (Zero data harvesting, zero sales)Sells user contact and income data to aggressive mortgage brokers
Ad ClutterClean, zero video ads, zero spam popupsOverwhelmed with predatory refinancing banners
Pricing & Signups100% Free Forever with no account requiredRequires email/phone number to view maximum purchase price
Operational Guide

Troubleshooting Common Issues & Edge Cases

Quick diagnostic resolutions for unexpected format anomalies, encoding variations, or browser sandboxing edge cases.

⚠️ Issue: What is the 28/36 rule in mortgage lending?

Resolution: The 28/36 rule states that your monthly housing costs (PITI) should not exceed 28% of your gross monthly income, and your total monthly debt payments (housing + student loans, cars, cards) should not exceed 36%.

⚠️ Issue: How does existing debt lower my maximum home price?

Resolution: Lenders cap your total monthly debt at ~36% to 43% of gross income. Every $100 in existing monthly car or student loan payments reduces the monthly mortgage payment you qualify for, shrinking your purchase price by approximately $15,000 to $20,000.

⚠️ Issue: Why is property tax factored into home affordability?

Resolution: Property taxes are a legally mandatory recurring obligation paid via escrow alongside your mortgage. Higher property taxes consume a larger portion of your allowed monthly housing payment, directly reducing the maximum loan amount lenders will issue.

Knowledge Base

Frequently Asked Questions (FAQ)

Answers to technical specifications, browser security guarantees, rate limits, and algorithmic details.

What is the 28/36 rule in mortgage lending?

Lenders prefer that monthly housing costs do not exceed 28% of gross monthly income, and total debt payments do not exceed 36%.

What does PITI stand for?

PITI stands for Principal, Interest, Property Taxes, and Homeowners Insurance—the four components making up a standard monthly mortgage payment.

How do monthly debts like student loans affect my affordability?

Higher monthly debt obligations reduce your available borrowing capacity under back-end DTI limits, shrinking your maximum qualifying loan amount.

Is any income or credit information stored?

No. All underwriting computations run strictly in your local device memory without network transmissions or credit checks.

What credit score is required to qualify for conventional mortgages?

Conventional loans backed by Fannie Mae generally require a minimum credit score of 620. Government-backed FHA loans allow scores as low as 580 (with 3.5% down), while prime interest rates typically require a 740+ score.

Can I buy a home with less than 20% down payment?

Yes. Conventional loans allow down payments as low as 3% to 5%, and FHA loans require 3.5%. However, down payments under 20% incur monthly Private Mortgage Insurance (PMI) until you reach 20% home equity.

Does this calculator factor in HOA dues?

Yes. In the loan settings, you can enter monthly Homeowners Association (HOA) fees. These are treated by lenders as part of your total monthly housing obligation.

What is the difference between gross income and net income for mortgages?

Mortgage lenders always underwrite loans based on your Gross Income (total income before taxes and retirement deductions), rather than your net take-home pay.

Is any personal or financial information stored by InnoxTools?

None whatsoever. All calculations execute locally inside your browser's RAM memory. No financial numbers, incomes, or credit inquiries are ever logged or transmitted.

Architectural Whitepaper & Performance Benchmarks

In-Depth Engineering Architecture & Execution Standards for Home Affordability & Max Mortgage Calculator

An authoritative technical examination of the algorithmic foundations, browser sandboxing primitives, and zero-telemetry protocols powering Home Affordability & Max Mortgage Calculator across desktop and mobile platforms.

Deterministic Memory Sandboxing & Client Privacy

Unlike conventional online utility platforms that transmit user files, code snippets, financial metrics, and confidential data over the public internet to third-party microservices, Home Affordability & Max Mortgage Calculator on InnoxTools executes entirely within your browser's isolated runtime environment. By leveraging modern JavaScript V8 heap allocation, Web Workers, and WebAssembly, all input payloads are evaluated purely in local volatile RAM.

Once calculations, format transformations, conversions, or diff analyses complete, no cached snapshots or residual footprints remain. Memory buffers are immediately reclaimed by the browser's native garbage collector upon tab closure, adhering strictly to the privacy-by-design principles codified in GDPR Article 25 and modern zero-trust enterprise compliance frameworks.

Zero-Latency Hardware Execution & Algorithmic Efficiency

Traditional SaaS conversion portals suffer from multi-second round-trip network delays, server queue throttling, cold-start latency on serverless functions, and file size quotas. In contrast, Home Affordability & Max Mortgage Calculator achieves near-zero latency by performing raw computations directly on the client machine's CPU and GPU cores without intermediate HTTP transport.

Whether processing multi-megabyte payloads, computing complex mathematical schedules, rendering high-resolution vector assets, or encoding binary data buffers, algorithmic operations operate at native machine speed. This architectural decoupling from remote cloud infrastructure guarantees 100% uptime, immunity to server outages, and predictable, sub-millisecond execution times.

Standard Operating Protocols & Workflow Integration

To maximize productivity when integrating Home Affordability & Max Mortgage Calculator into professional software development, financial auditing, document publishing, or creative workflows, consider these recommended standard operating protocols:

  • Air-Gapped Offline Execution: Because all necessary scripts and WASM binaries cache locally via modern browser service workers and HTTP caching headers, Home Affordability & Max Mortgage Calculator remains fully operational in offline environments, secure intranet stations, or high-security financial labs.
  • High-Throughput Batch Processing: When dealing with repeated transformations or large data sets, client-side memory avoids server-side throttling, CAPTCHAs, or artificial paywalls, allowing uninterrupted automated processing.
  • Standardized Verification: All output formats generated by Home Affordability & Max Mortgage Calculator conform strictly to authoritative industry standards (including W3C web recommendations, RFC specifications, ISO document formats, and IEEE 754 floating-point arithmetic).
Enterprise Software Engineering

Turn your ideas into high-performance software with INNO XPERT

InnoTools is developed by the engineering team at INNO XPERT. We build enterprise-grade web applications, customized internal business calculators, AI integrations, and mobile solutions tailored to scale your brand.

Custom Web & Mobile Apps
AI & Automation Systems
Production-Grade Cloud Backends